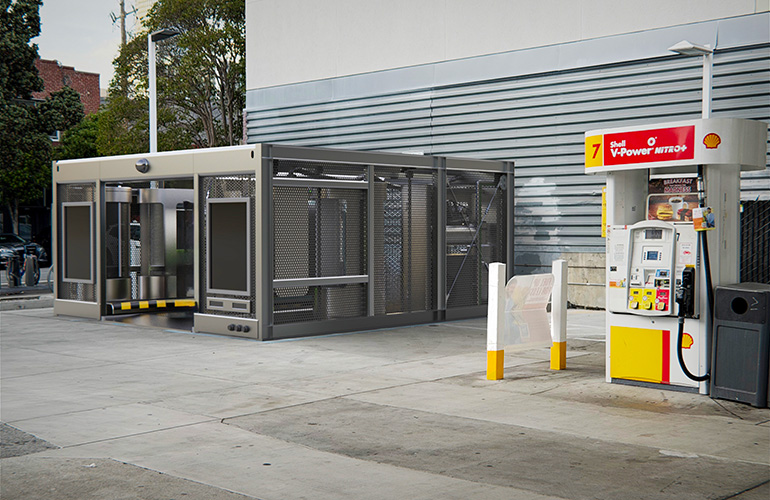
In the future, robotaxis will have cleaning and reset stations available throughout their operational territory. | Credit: Aseon Labs
Robotaxis are proven. Waymo has logged more than 220 million autonomous miles and, by its own count, has more than 94% fewer serious injury crashes than human drivers. It gives around half a million paid rides a week and is expanding to more cities.
So the question has moved from “Does this work?” to “How does this get everywhere?”
Waymo is in 14 cities. Uber is in over 15,000. Uber did 3.9 billion trips last quarter. It processes Waymo’s entire weekly ride volume every 17 minutes. Driving software and vehicle supply have billions pointed at them. Almost nobody is funding the least glamorous problem: what happens to the cars between rides.
The pit is across town
No Formula 1 team drives back to the factory for new tires. The pit is at the track; the car is out in seconds. A robotaxi finishes a ride, discovers a spilled latte on the back seat, and drives up to 15 miles, empty, to a centralized depot to be cleaned, charged, and inspected.
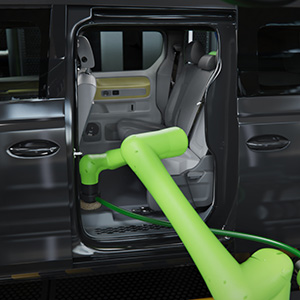
A fully autonomous pod cleans and recharges a robotaxi. | Credit: Aseon Labs
Each reset costs roughly two hours. California data shows the cost: of 86 million Waymo miles reported through 2025, only 54% carried a passenger.
Not every empty mile is a depot run, but every depot run is an empty mile. Autonomous on the road, manual the moment it needs servicing. That is where scale breaks.
That worked for one company in a few cities. It cannot carry an industry to thousands, for three reasons.
The land is gone. The site a depot needs, industrial-zoned and wired for power, is the one everyone wants. Brokers report data center developers outbidding industrial buyers for powered parcels. An operator entering a new city walks into a house auction against the likes of Microsoft and Amazon.
The clock is against you. California’s regulator targets six months just to energize a standard charging site. A new circuit runs 1.9 years; a substation upgrade, 2.8; a new substation, 8.9. Per city. Across thousands of cities, that is decades.
Every city is different. Phoenix is a sprawl of sunlit parking lots. Zurich is a medieval street plan with a planning committee. Riyadh has heat that cooks batteries and dust that coats sensors by lunchtime.
No single design fits them all, so the industry builds a bespoke depot in each. Fifteen cities, 15 projects. Fifteen thousand, and the model collapses under its own paperwork.
Waymo is the beginning, not the shape
Waymo did everything itself. It designed the driver, retrofitted the cars, ran the fleet, built the app, staffed the depots. Even Waymo has shed two layers: Zeekr builds its Ojai vans, while Moove, Avomo, Avis, and Flexdrive run its depots.
The next wave of autonomous vehicles is built by specialists. Wayve, Nuro, and Mobileye sell brains. Carmakers put those brains in their own cars: Nissan with Wayve, Lucid with Nuro, Volkswagen with Mobileye, Mercedes with NVIDIA. Uber supplies riders to more than 30 autonomous partners. The result is not one fleet of one vehicle but dozens of fleets of different vehicles.
I spent years building a battery-swapping network for shared scooters, when hundreds of operators ran a few manufacturers’ vehicles in thousands of cities. Nobody won because they had a better scooter. The survivors could charge, repair, and reposition tens of thousands of vehicles daily. The vehicle was never the hard part. The operations were.
Robotaxis are the same play at a hundred times the price. A Wayve-powered Nissan on Uber in Zurich still needs charging, cleaning, and inspection several times a day, and no one wants to buy an industrial lot there. Without the infrastructure, none of it runs.
 Register now and help us celebrate 20 years of RoboBusiness!
What unlocking scale for robotaxis looks like
The shipping container did not make ships faster. It made every port the same, and that unlocked global trade. Robotaxis need their container, a standard unit of servicing infrastructure that fits in a bay or two, deploys in days, not years, is configured per city, not re-engineered, and serves any fleet on any network, as one cell tower serves every carrier.
Full disclosure: My company, Aseon Labs, is building a robotic charging, cleaning, and inspection station that arrives on a flatbed, designed to go live within a day. We are early and will not be the only ones. The argument does not depend on us. It depends on arithmetic: years per depot, per city, for an industry that needs thousands.
Every robotics demo ends the same way: Someone off camera walks in with a charging cable. Robotaxis are the first robot at commercial scale to learn the demo was never the hard part. Andreessen Horowitz raised $1.1 billion for the physical buildout of AI. Software ate the world. Now it needs somewhere to park.
The cars can already drive themselves. They still cannot charge, clean, or inspect themselves. Somebody has to build the pit.
About the author
Dan Keene is co-founder of Aseon Labs, a Y Combinator-backed company building distributed robotic servicing stations for autonomous vehicle fleets.
He previously co-founded Pushme, the battery-swapping network acquired by TIER in 2020.
Tell Us What You Think!